


If you held off on equipment purchases in 2024 or 2025 because the bonus depreciation rules were getting worse every year, the situation has changed. The One Big Beautiful Bill Act restored 100% bonus depreciation for qualifying property acquired after January 19, 2025. That reverses a phase down that had taken the rate to 40% in 2025 and was scheduled to hit zero by 2026.
Under prior law, every year that passed cost you more. A $100,000 piece of equipment bought in 2024 generated an $80,000 first year deduction at the 80% rate. In 2025 that dropped to $40,000 before the OBBBA restored it. Starting with purchases made after January 19, 2025, the full $100,000 is deductible in the year you place the equipment in service.
Section 179 also got a significant upgrade. The deduction limit doubled from $1.25 million to $2.5 million, and the phase out threshold was raised to $4 million. For most small and mid size retail and CPG businesses, the Section 179 limit was never the constraint, but the higher ceiling matters for growing businesses and multi location operators making large capital investments.
There is a new provision worth knowing about if you run a CPG manufacturing operation or are considering building one. The OBBBA created a 100% first year deduction for qualified production property which includes buildings used in manufacturing or production activities if construction begins before January 1, 2029. This is a significant change from the standard 39 year depreciation schedule for commercial buildings and creates a compelling planning window for CPG brands considering facility investments.
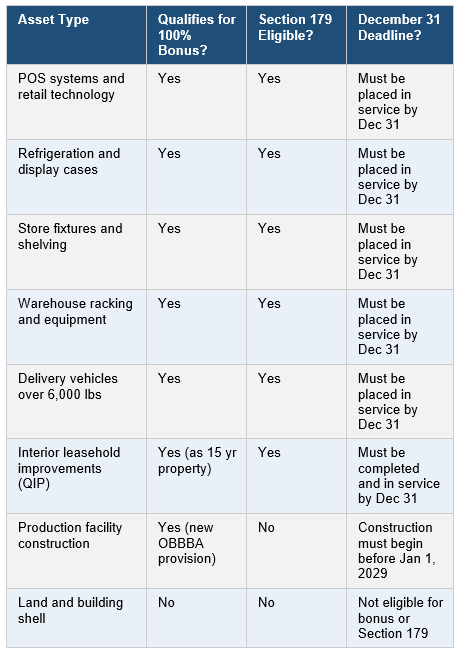
What Qualifies and When You Need to Act
One nuance worth knowing: bonus depreciation can create or increase a net operating loss, which carries forward indefinitely. Section 179 cannot create a loss it is limited to your taxable income for the year. For a retailer in a year with strong profits, both tools work. For a retailer in a marginal year, bonus depreciation may be the better choice because it does not have the taxable income limitation.
The December 31 deadline is the placed in service date, not the purchase date. Equipment ordered in December and delivered in January does not qualify for 2026. If you are planning a significant purchase and need it to count this year, work backward from your vendor’s lead time and get your order placed with enough runway to have the equipment installed and operational before year end.
Bottom Line: The window to deduct 100% of a qualifying asset purchase in the year of purchase is open and has no current expiration for equipment. If you have been putting off a capital investment, the tax math has never been better than it is right now. Run the numbers with your CPA and make the placed in service deadline work for you, not against you.