


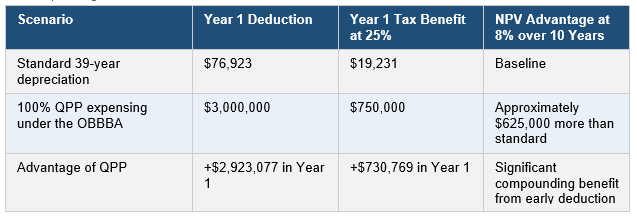
One of the least publicized provisions in the One Big Beautiful Bill Act is one of the most valuable for CPG companies that own or are planning to build manufacturing facilities. Under the new Qualified Production Property rules in Section 168(n), certain newly constructed or renovated buildings used for domestic manufacturing, production, or refining qualify for 100% bonus depreciation in the year they are placed in service. Under standard tax treatment, a commercial building is depreciated over 39 years. The QPP provision replaces that with a full first-year deduction. On a $3 million facility, that is the difference between a $76,923 deduction in year one and a $3 million deduction in year one.
To qualify, the property must be used as an integral part of a domestic production activity that results in a substantial transformation of the underlying materials. For CPG operators, this covers food and beverage production facilities, personal care and cosmetics manufacturing plants, nutritional supplement production facilities, and similar infrastructure. Office space, retail areas, administrative functions, and software development spaces within the same building are excluded from the calculation. The timing requirements are strict. Construction must begin after January 19, 2025 and before January 1, 2029. The property must be placed in service before January 1, 2031. A facility that starts construction in early 2028 but is not completed until 2031 does not qualify.
Year 1 tax benefit comparison for a $3 million manufacturing facility under standard depreciation versus QPP expensing.
Finance teams considering facility projects should start modeling this now. Full first-year expensing of a major capital investment creates a large deduction that may exceed current-year taxable income, producing a net operating loss that carries forward to future years. The multi-year tax impact, the state tax implications in states that do not conform to federal treatment, and the interaction with Section 179 elections and other depreciation choices all need to be worked through before you finalize the project structure. Engage a tax advisor with manufacturing and CPG experience before you break ground.
Bottom Line: The Qualified Production Property provision gives CPG manufacturers a chance to fully expense a new facility in the year it opens, rather than depreciating it over 39 years. Construction must start before the end of 2028. If you have a facility project on the horizon, evaluate this now. The planning window is finite.