


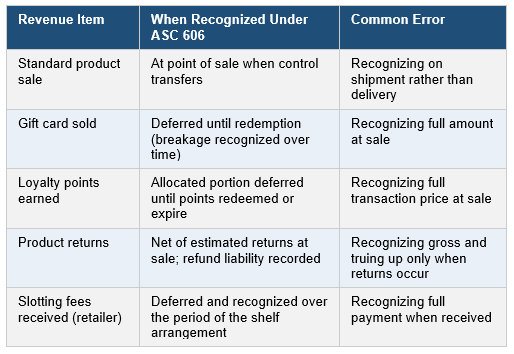
ASC 606 changed how retail and CPG businesses recognize revenue by requiring that revenue reflect the amount the company expects to be entitled to receive in exchange for goods or services transferred to a customer. For most simple retail transactions, this is unchanged. For loyalty programs, gift cards, returns, and variable consideration, the standard requires specific accounting treatment that many smaller retailers are not fully applying.
Variable consideration must be estimated at the time of sale. For a retailer with a 15% return rate on a product line, the full price cannot be recognized at sale as an estimated return allowance must be accrued. The refund liability and the right-of-return asset (representing the expected cost of goods coming back) must both be recorded.
Gift cards create a deferred revenue liability at the time of purchase. Revenue is recognized only when the card is redeemed. For cards that are never redeemed breakage revenue may be recognized proportionally as redemptions occur (if breakage is estimable) or when the probability of redemption becomes remote.
Bottom Line: If your revenue recognition policy for gift cards and loyalty programs hasn’t been reviewed since ASC 606 went into effect, it probably needs attention. The standard is fully effective for all entities and the SEC and lenders are increasingly asking about it in due diligence.