


The IRS assesses billions of dollars in penalties each year for failure to file, failure to pay, and failure to deposit payroll taxes on time. What most retail and CPG business owners do not know is that many of these penalties are removable either automatically through first-time abatement or through a reasonable cause argument.
First-Time Penalty Abatement (FTA) is an administrative waiver the IRS grants to taxpayers who have a clean compliance history. To qualify, you must have filed all required returns (or a valid extension) for the prior three years, paid or arranged to pay all prior balances, and have no prior penalty assessments in the three prior tax years. FTA applies to failure-to-file, failure-to-pay, and failure-to-deposit penalties.
FTA is not advertised by the IRS. You have to request it. The request can be made by calling the IRS directly or by submitting a written request. If you have a clean history and your CPA has not asked about FTA when a penalty appears, ask them to.
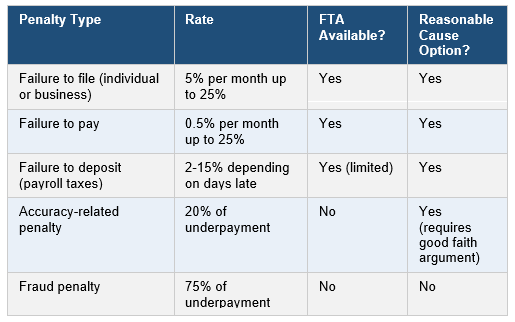
Reasonable cause relief is available when a taxpayer can show they exercised ordinary business care and prudence but still could not comply. Events like a serious illness, natural disaster, reliance on professional advice, or a fire that destroyed records can support a reasonable cause argument. The IRS evaluates each case on its facts.
Bottom Line: If you receive an IRS penalty notice, do not just pay it. Ask your CPA whether FTA or reasonable cause relief applies. A penalty that can be removed with a phone call or a one-page letter is not a cost of doing business it is an optional expense.