


There is a change that took effect on January 1, 2026 that most retail and CPG business owners have not adjusted for yet, and it is showing up in budgets as a silent cost increase. The employer provided meals deduction that has been phasing down since 2018 finally hit zero. If your company provides snacks, beverages, or meals to employees at the workplace, you are now paying those costs with after tax dollars and you cannot deduct them.
Here is the history. Before the Tax Cuts and Jobs Act of 2017, employer provided meals on business premises were 100% deductible when provided for the convenience of the employer. The TCJA reduced that to 50% starting in 2018 and scheduled it to drop to zero starting in 2026. It dropped. No restoration was included in the One Big Beautiful Bill Act. The breakroom coffee and the snack bar you stock for your team are now non deductible fringe benefits for your business.
The bigger exposure is for employers who run more structured food programs. Office cafeterias, employer subsidized meals, catered working lunches for employees, and overtime meal policies where the company buys dinner for staff working late all of these had partial deductibility before 2026. Now they have none, and in many cases the value is now taxable to the employee as a fringe benefit as well.
What You Can Still Deduct and What You Cannot
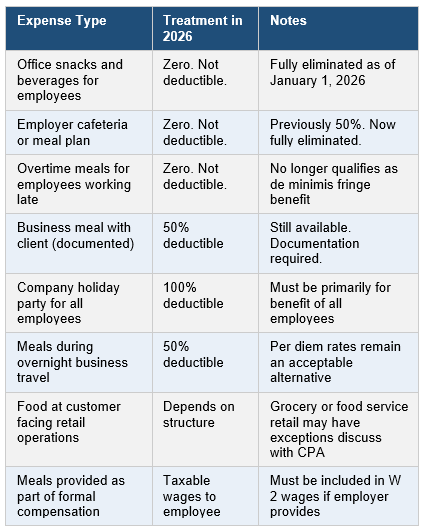
If your 2026 budget still reflects a 50% deduction for employee meal programs, you have a variance building up right now. The simplest fix is to reforecast the after tax cost of any employee food program and decide whether the benefit still justifies the full unsubsidized cost. In some markets and industries, the benefit is worth it for retention. In others, it made sense only because of the subsidy.
One alternative worth considering: convert your informal snack program into a formal Section 132 de minimis fringe benefit with a documented value low enough to still meet the threshold. The IRS has not updated the specific dollar limit for de minimis fringe benefits in years and the guidance is fact specific, but a genuinely minimal snack allowance may still qualify. Get your CPA to confirm the current parameters before relying on this.
Bottom Line: January 1, 2026 was the end of the employer provided meals deduction. If your budget still shows a 50% deduction for employee food programs, fix it now. The cost is real and the deduction is gone. The company holiday party is still 100% deductible. The breakroom snacks are not.