


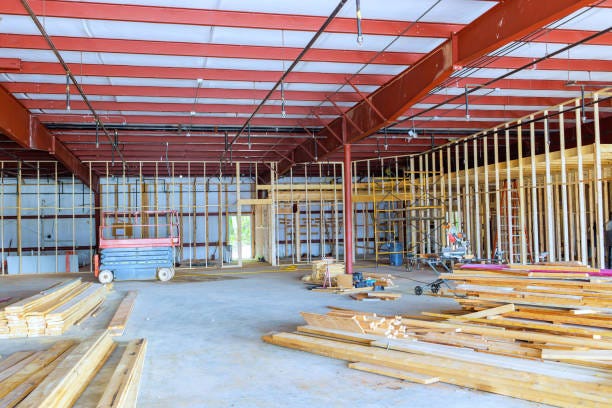
When you build out a retail space, the improvements you make to the interior of a building you lease are called Qualified Improvement Property (QIP). Under current law including the retroactive fix made in 2020 and now made permanent by the OBBBA QIP has a 15-year depreciable life and qualifies for 100% bonus depreciation in the year placed in service.
This is significant. Before the QIP fix, tenant improvements in a leased space were depreciated over 39 years as regular commercial real estate. At 39 years, a $500,000 build-out generates about $12,800 in depreciation per year. At 15 years (and especially with 100% bonus depreciation), you deduct the entire $500,000 in year one.
QIP includes any improvement to the interior of a commercial building that is placed in service after the building was first placed in service. It excludes enlargements to the building, elevators, escalators, and internal structural framework. Nearly everything inside the four walls of your leased retail space qualifies.
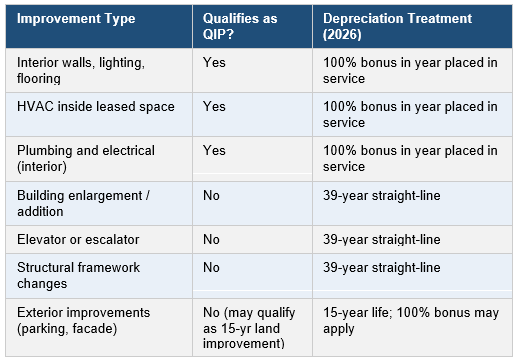
If you completed a store renovation in 2024 or 2025 and depreciated it over 39 years, you may be able to file an amended return or accounting method change (Form 3115) to capture the missed bonus depreciation. This is a common and legal catch-up.
Bottom Line: The next time you build out a retail space, every dollar of interior improvement potentially comes off your taxes in year one. Make sure your CPA knows the QIP rules before you capitalize the project at 39 years.